
The Long View: Love at First Hike? It Could Be
Wall Street has a knack for compressing complicated truths into memorable phrases. Few have proven as durable as the observation “Bull markets don’t die of old age; they are killed by the Fed.” However, economic expansions and the bull markets riding on them do not expire on a set schedule. Rather, they end when something breaks, which often happens when monetary policy is tightened past what the economy can bear.
As a result, many investors are understandably fearful of Fed tightening cycles. History shows that recessions historically come on average over a year after the Fed has finished hiking, meaning that the clock begins ticking on the first hike. But the alarm bells should not be going off today. The early stages of a tightening cycle typically coincide with continued economic growth, rising corporate profits and positive equity returns.
A Fed that is raising rates is almost by definition a Fed that sees strength. When the economy is strong enough to prompt a hike, corporate revenues are usually growing, operating leverage is positive and margins are often expanding. The first hike typically leaves those conditions intact and signals that policymakers want to moderate growth before excesses become problematic.
Milton Friedman famously described monetary policy as operating with “long and variable lags,” with their full effect taking 12 to 18 months to materialize. Today that lag may run even longer than usual because much of the economy is unusually insulated from higher rates. For example, many homeowners are locked into low fixed-rate mortgages, while many corporations termed out their debt in recent years when rates were low. As a result, the drag from higher interest expense won’t be felt as quickly.
Additionally, consumers in aggregate have strong balance sheets and should be able to absorb modestly higher borrowing costs without cutting back on spending. For struggling consumers, untapped borrowing capacity could act as a buffer to support consumption — over the past few years consumer credit has been growing at the weakest non-recessionary levels in history.
Exhibit 1: Consumer Not Tapped Out
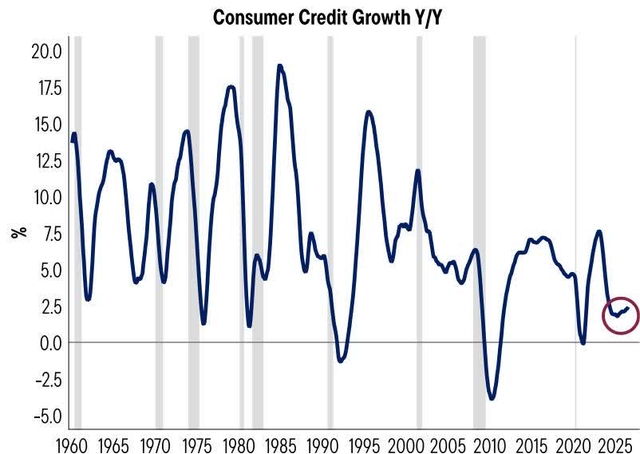
Sources: Macrobond, Federal Reserve. Data as of September 8, 2026, latest available as of September 30, 2026.
Note: Two-Quarter Moving Average. Gray shading reflects recessionary periods.
Higher Rates Come at a Moment of Strength
Markets have already priced in the new hiking cycle. Federal-funds futures have swung from expecting multiple rate cuts in February 2026 to pricing more than four total hikes today; the expected federal-funds rate for July 2027 has risen by 165 basis points over the same time frame. That repricing accounts for part of the recent rise in long-term Treasury yields.
Expectations of additional hikes are not the only thing driving long-term rates higher: as we noted last month, the rise in longer-term bond yields can be characterized as normalization after the period of secular stagnation following the Global Financial Crisis (GFC). Importantly, investors have seen this higher-rate story before: the 10-year Treasury yield has spiked into the high 4% range in each year since the Fed’s 2022 hiking cycle began. Despite that headwind, the S&P 500 Index has continued to advance, with robust earnings growth more than offsetting the drag from contracting valuation multiples. Higher yields, in other words, have so far been a test the market has passed rather than a blow it could not absorb.
Exhibit 2: The Honey Badger Market
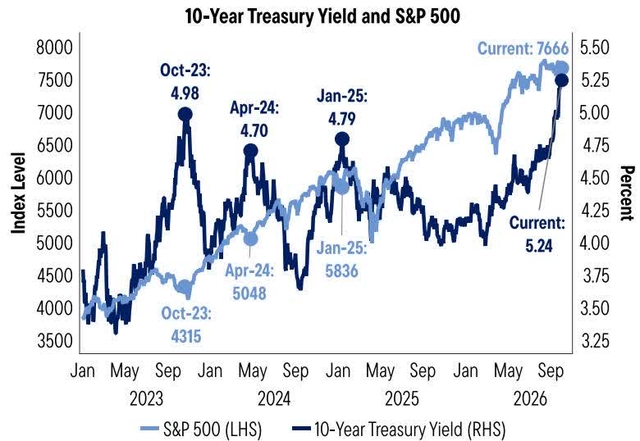
Data as of October 2, 2026. Sources: U.S. Department of Treasury, S&P Global, Macrobond.
The 10-year yield is an incomplete guide to what credit actually costs in the real economy. Most of the borrowing rates that households and businesses pay remain below the peaks reached in 2023, the last time the 10-year neared 5%. Bankrate’s average 30-year fixed mortgage rate now stands at 7.3%, compared with 8.1% during that earlier peak. Investment-grade corporate bonds yield about 6.0% versus 6.4% in 2023, and high-yield bonds 8.4% versus 9.5%. These are the rates that consumers and businesses actually pay: they shape decisions to buy homes, fund expansions and refinance debt. With these rates still below peak levels seen just three years ago, we believe higher rates will weigh less on the underlying economy than the move in Treasurys alone suggests.
Exhibit 3: Borrowing Rates Below Peak … But Not For Uncle Sam
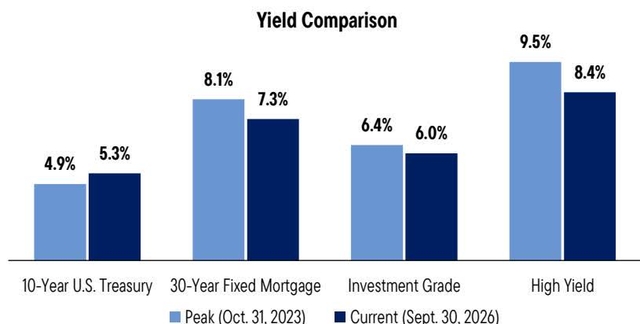
Data as of September 30, 2026. Source: Bloomberg, U.S. Department of Treasury, Bankrate, FactSet, Macrobond.
Note: 10-Year U.S. Treasury Yield represented by the Federal Reserve 10-year yield, 30-Year Fixed Mortgage represented by the Bankrate 30-year fixed mortgage rate, average interest rate, Investment Grade Yield represented by the Bloomberg US Corporate Investment Grade – YTW, High Yield represented by the Bloomberg US Aggregate Credit – Corporate – High Yield (1983) – YTW.
The beginning of a tightening cycle and the end of an economic cycle are typically separated by a considerable period. The recession, if one comes, is the product of the cumulative hiking cycle and how long rates are held in restrictive territory. The strength of the economy that the Fed is hiking into is a pivotal consideration when assessing the durability of an expansion during a hiking cycle. Thankfully, the starting point for this hiking cycle is one of strength for the U.S. economy, as evidenced by the ClearBridge Recession Dashboard. At present, the dashboard sports a strong overall green expansionary signal with Job Sentiment the sole indicator in red territory. There were no individual indicator changes last month.
Exhibit 4: U.S. Recession Dashboard
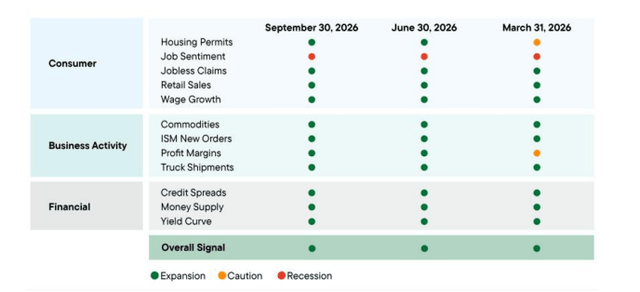
Data as of September 30, 2026. Sources: BLS, Federal Reserve, Census Bureau, ISM, BEA, American Chemistry Council, American Trucking Association, Conference Board, Bloomberg, CME Group, FactSet and Macrobond. The US Recession Dashboard was created in January 2016. References to the signals it would have sent in the years prior to January 2016 are based on how the underlying data was reflected in the component indicators at the time.
What often determines how much economic or market pain follows is the overall magnitude of the hike cycle. Tightening of 425 basis points (bps) in 2004–06 preceded the GFC, while the Fed raised rates by 525 bps in 2022–23. That latter hike cycle came at the fastest pace in four decades and pushed stocks into a bear market, although the economic expansion outlasted the monetary tightening and continues to the present day.
Today, federal funds futures price roughly 115 bps of cumulative hikes occurring in just over one year, an even more aggressive path than what is implied by the “Fed dots.” If the market pricing comes to fruition, this hike cycle would be the most modest in modern history, which should limit economic damage. We believe this would also be conducive to the typical pattern of early volatility and modest multiple compression, followed by earnings-driven gains, playing out in the months following the initial hike.
Market dynamics over the past year already resemble that pattern and look very different from the post-GFC era. Over the past 12 months the S&P 500 has been supported by materially stronger revenue and earnings growth expectations, while valuations have compressed rather than expanded. In our view, the opportunity presented by stronger fundamentals combined with P/E derating is attractive for long-term investors, should the underlying drivers of corporate profits remain healthy. With the potential for continued upside from AI spending and adoption, U.S. equities may be poised to enter a new regime.
Exhibit 5: Stronger Fundamentals, Cheaper Multiples
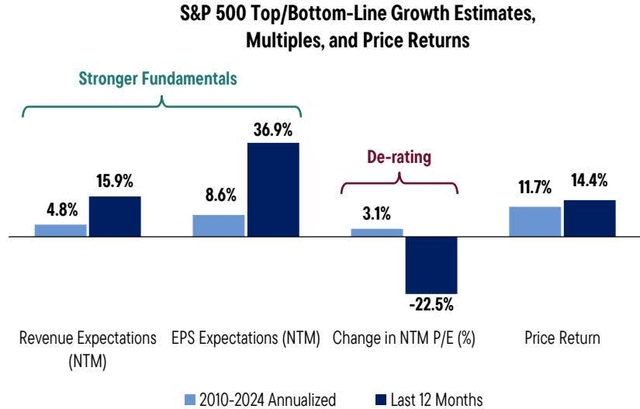
Data as of September 30, 2026. Sources: S&P, FactSet.
Strong Earnings Could Broaden the Market
Investors often treat peak earnings growth like the first rate hike: a warning sign that the good times are ending. However, history shows that the peak itself is less important than where earnings settle afterward. Since 1980, the S&P 500 has returned 19.6% on average in the year after peak EPS growth when EPS growth remained above 10%, versus 6.1% when EPS growth slowed below 10%. Consensus suggests that peak EPS growth is upon us, but expectations for the next 12 months currently stand at 18.7%, comfortably above the 10% threshold and well within the stronger of the two historical cohorts.
Exhibit 6: Not All Peaks Are Equal
Sources: S&P, Bloomberg.
Where that earnings growth comes from matters tremendously for investors. The Magnificent Seven’s multiyear outperformance has rested on superior earnings growth that consistently outpaced the broader market, justifying elevated valuations and an outsize share of index returns. Consensus forecasts, however, show this earnings advantage is expected to fade in 2027 as growth for the S&P 493 and S&P 1000 (SMID) converges with the Magnificent Seven. A narrower gap could broaden market leadership as investors revisit areas that have lagged during the past few years of mega cap dominance.
Exhibit 7: Closing the Gap
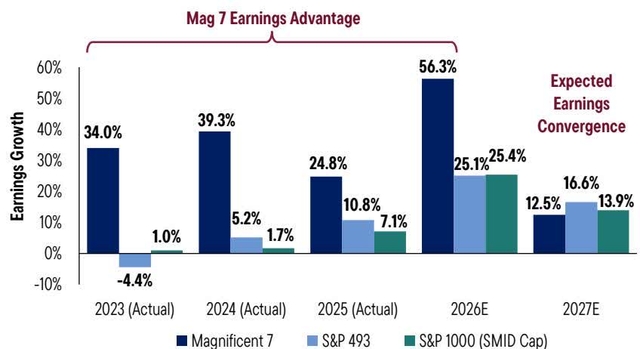
The term “consensus” within the capital markets industry refers to the average of earnings estimates made by professionals. Magnificent 7 data refers to the following set of stocks: Microsoft (MSFT), Amazon (AMZN), Meta (META), Apple (AAPL), Google parent Alphabet (GOOGL), Nvidia (NVDA), and Tesla (TSLA). Data as of September 30, 2026. Sources: FactSet, S&P.
If realized, this shift would carry important implications for equal- versus cap-weighted leadership in the S&P 500, which has oscillated frequently throughout history. Although the past decade has predominately witnessed cap-weighted leadership, history shows that equal-weight could be poised to reclaim the baton. Since 1990, the S&P 500 Equal Weight Index has outperformed 70% of the time during rolling 10-year periods, as concentrated leadership has tended to give way to broader participation. If the Magnificent Seven versus S&P 493 earnings gap keeps narrowing as expected, we believe the backdrop would become increasingly supportive of a sustained period of equal-weight outperformance.
Exhibit 8: Equal-Weight To Take The Baton?
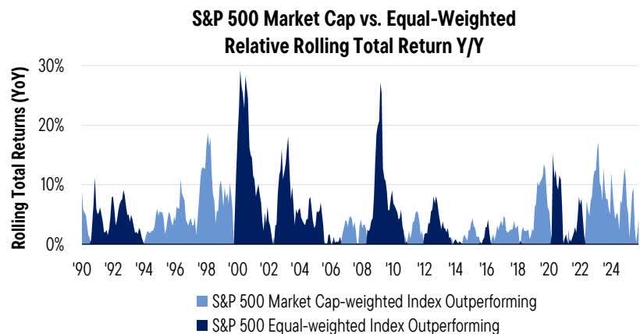
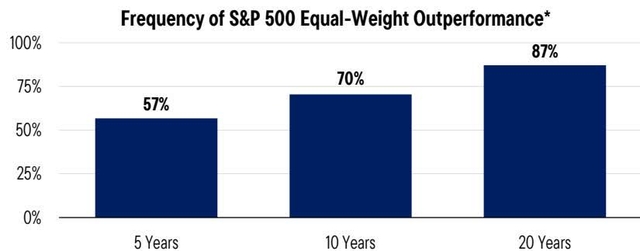
*Note: Annualized monthly total return indices.
Sources: FactSet, S&P Dow Jones Indices; analysis by Franklin Templeton Institute and Global Research Library.
From December 31, 1990, to September 30, 2024.
The case for broadening also extends beyond U.S. borders. Historically, non-U.S. equities have proven resilient in the year following the start of a Fed rate hike cycle, though the magnitude of the cycle is an important factor. A shallower hike cycle is less likely to tighten global financial conditions than an aggressive one while rate hike expectations for this cycle remain modest by historical standards. Even if the market is directionally but not precisely right about the size of this cycle, history suggests that non-U.S. developed equities could see outsize benefits, giving investors another way to participate in broadening market leadership.
Exhibit 9: Non-US Equities After the Hike
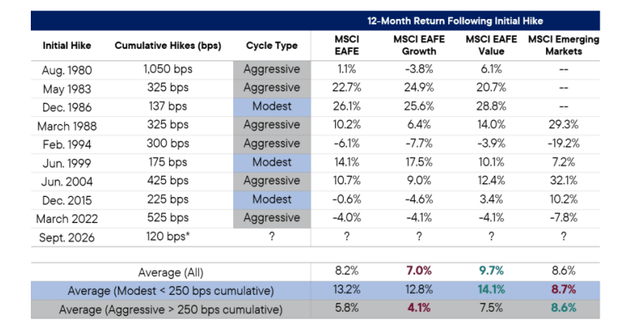
*Cumulative current cycle hikes based on peak Fed Fund futures market pricing as of September 30, 2026.
Sources: FactSet, Bloomberg, MSCI.
First Hike Is Not a Fatal Blow
With all of that said, the adage about the Fed and bull markets still holds. The Fed may kill bull markets in the end, but the first hike is not the fatal blow. We believe the adage is most useful in pointing investors toward general, not specific, parts of the cycle. A deeper analysis shows that the danger zone for investors typically comes after the Fed has finished hiking interest rates, when monetary policy is well into restrictive territory and the long and variable lags have passed.
Signs that tighter policy is biting include an inverted yield curve, widening credit spreads and a rollover in leading indicators of employment and activity. None of these classic signs are evident today and, in our view, a modest hiking cycle (if realized) won’t materially dent today’s resilient economic backdrop in the year ahead.
This next chapter of the ongoing economic expansion, one marked by tightening policy, has historically rewarded investors who stay focused on earnings, watch for late-cycle warnings and take advantage of the volatility that typically follows an initial hike. An updated version of the adage that old age doesn’t kill bull markets should probably include something to the effect that a young hiking cycle rarely does either.
Original Post